
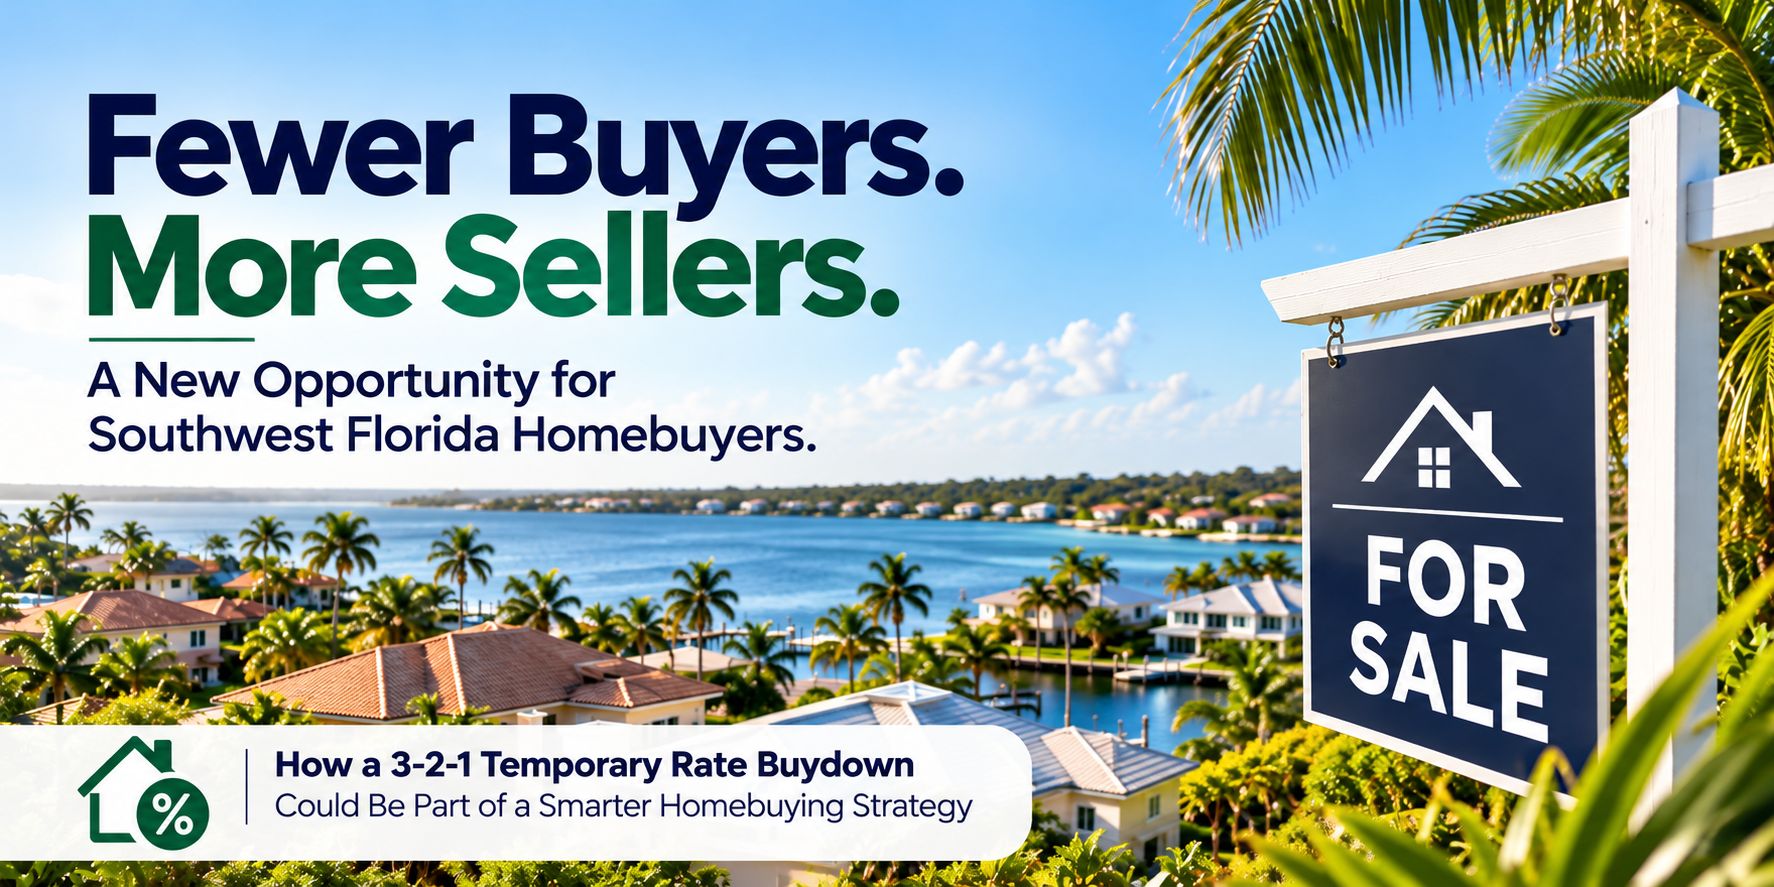
Why today's shifting housing market could give buyers more negotiating power, and how a 3-2-1 temporary rate buydown could be part of a smarter homebuying strategy.
For the past several years, homebuyers have faced a challenging combination of elevated mortgage rates, rising home prices, and affordability concerns. Many have decided to wait, hoping conditions will improve.
But something interesting is happening in the housing market.
There are now significantly more sellers than buyers competing in the market.
That shift could create opportunities for homebuyers in Venice, North Port, Port Charlotte, Punta Gorda, and throughout Southwest Florida.
And here's the important part: Taking advantage of those opportunities isn't necessarily about finding the lowest price or waiting for mortgage rates to fall. It's about understanding how to negotiate the right combination of price, financing, and seller concessions.
A Record-Breaking Shift in the Housing Market
According to an August 2026 report from Redfin, the number of active homebuyers in the United States fell to its lowest level in the company's records.
At the time, sellers outnumbered buyers by approximately 51%.
But the trend didn't stop there.
Redfin's September report revealed that the gap had widened even further. In August 2026, there were an estimated:
- 1.53 million home sellers
- 972,300 homebuyers
- 57.9% more sellers than buyers
This represented the largest buyer-seller imbalance in Redfin's records, which date back to 2013.  Redfin Real Estate News
Think about what that means.
When more buyers are competing for fewer homes, sellers generally have the advantage. Buyers may feel pressured to act quickly, offer above asking price, or limit their requests.
But when there are more sellers competing for fewer buyers, the conversation changes.
Sellers may become more receptive to negotiating, particularly when their homes have been sitting on the market.
That doesn't mean every seller is desperate or that every home is a bargain. It simply means qualified buyers may have more opportunities to negotiate favorable terms.
What Does This Mean for Southwest Florida?
Our local housing market has experienced its own changes as buyers and sellers adjust to higher borrowing costs and shifting affordability.
Across communities like Venice, North Port, Port Charlotte, Punta Gorda, and Sarasota, buyers should be looking beyond the asking price to evaluate the full opportunity.
Florida Realtors' August 2026 statewide report showed a market that was stabilizing rather than collapsing. Single-family closed sales declined approximately 1.5% year over year, while the statewide median sale price increased slightly to $415,000.
Interestingly, statewide single-family inventory was also down 13% compared with August 2025.  Florida Realtors
This is an important reminder that national headlines don't always tell the full local story.
A home in Venice may experience very different demand than a property in North Port or Port Charlotte. Even within the same community, price range, property condition, insurance costs, and time on market can significantly influence a seller's willingness to negotiate.
The opportunity isn't simply finding a home with a reduced asking price. It's identifying sellers who may be willing to help improve your overall cost of homeownership.
Seller Concessions: An Opportunity Buyers Should Understand
When most people think about negotiating a home purchase, they immediately think about offering less than the asking price.
That's certainly one strategy, but it's not the only one.
Another option is negotiating seller concessions.
Seller concessions are contributions that a seller agrees to make toward certain eligible costs associated with the buyer's mortgage transaction.
Depending on the loan program and transaction, these contributions may help cover closing costs, prepaid expenses, discount points, or a temporary interest rate buydown.
Here's where things get interesting.
Instead of focusing exclusively on reducing the purchase price, buyers may be able to negotiate a contribution that helps lower their mortgage payments during the first few years of homeownership.
And one strategy worth exploring is the 3-2-1 temporary interest rate buydown.
What Is a 3-2-1 Temporary Rate Buydown?
A 3-2-1 temporary buydown is a financing arrangement designed to reduce the borrower's effective mortgage payment during the first three years of the loan.
Here's how it works:

Percentage-point reductions in the rate used to calculate the borrower's payment. The mortgage note rate itself does not change.
For example, during the first year, the buyer's payment is calculated using an interest rate three percentage points below the actual note rate. During the second year, the reduction is two points, and during the third year, one point.
Beginning in year four, the borrower makes the full payment based on the original note rate.
The funds needed to cover the temporary payment difference are deposited into a designated buydown account at closing and applied over the three-year period.
Depending on the transaction and loan program, those funds may be provided through negotiated seller concessions.
It's important to understand that this is not a permanent interest rate reduction. The buyer must qualify for the mortgage using the full note rate, and the payment will increase according to the established schedule.
Fannie Mae's guidelines permit certain 3-2-1 temporary buydown structures, subject to eligibility, funding, and seller-contribution requirements.  Fannie Mae
Why Would a Buyer Consider This Strategy?
The first few years of homeownership can involve significant expenses.
Beyond the down payment and closing costs, buyers may face moving expenses, furniture purchases, maintenance, and other costs associated with settling into a new home.
A temporary buydown can provide lower initial principal-and-interest payments during that adjustment period.
For some qualified buyers, that additional monthly cash flow may be valuable.
But there's another important consideration.
A temporary buydown should never be used as a reason to purchase a home that isn't affordable at the full mortgage payment.
Buyers should be financially comfortable with the payment that begins in year four, regardless of what happens with future interest rates.
And while refinancing may become an option if market conditions improve, there is no guarantee that lower rates or favorable refinancing opportunities will be available.
The goal isn't to gamble on where mortgage rates might go. It's to make an informed financing decision based on today's numbers and your long-term financial goals.
Should You Negotiate a Lower Price or Ask for Seller Concessions?
This is one of my favorite conversations to have with homebuyers because the answer isn't always what people expect.
Imagine finding a home that checks all your boxes.
The seller is motivated, the property has been on the market for a while, and there's an opportunity to negotiate.
Would you be better off asking for a reduction in the purchase price or requesting seller concessions to help with financing costs?
The answer depends on several factors, including your down payment, loan program, available cash, financing terms, and how long you plan to own the property.
A lower purchase price can reduce the amount financed and potentially lower the monthly payment over the life of the loan.
Seller concessions, on the other hand, may help reduce upfront expenses or temporarily lower mortgage payments.
Neither strategy is automatically better.
In some situations, a combination of the two may produce the most favorable outcome.
That's why I believe the financing conversation should happen before submitting an offer, not after the contract has already been negotiated.
When your Realtor and mortgage lender work together, you can evaluate the numbers and structure an offer that supports your financial goals.
Don't Wait for the Perfect Market. Have a Strategy for the Market We're In.
There's an old saying in real estate that you can't perfectly time the market.
And while that may sound like a cliché, there's an important lesson behind it.
No one knows exactly where home prices or mortgage rates will be six months or a year from now.
What we do know is that housing-market conditions are constantly changing.
Today's market may offer qualified buyers negotiating opportunities that weren't as readily available when competition was more intense.
That doesn't mean everyone should rush out and buy a home.
But it does mean that buyers who have been waiting on the sidelines may benefit from taking another look at their options.
The right home, the right financing structure, and the right negotiation strategy can make a meaningful difference.
Let's Explore Your Options
If you're considering purchasing a home in Venice, North Port, Port Charlotte, Punta Gorda, Sarasota, or anywhere in Southwest Florida, I'd welcome the opportunity to help you understand your financing options.
Whether you're a first-time homebuyer, a veteran exploring VA financing, or a current homeowner planning your next move, my goal is to help you make an informed decision.
We'll look at your budget, available loan programs, and potential financing strategies, including whether a 3-2-1 temporary rate buydown makes sense for your situation.
Because buying a home isn't just about getting a mortgage. It's about making a financial decision that supports your future.
Share


RECENT ARTICLES
Free Guides & Resources
Our favorite kind of buyer? A confident one. Brush up on your loan knowledge, get an accurate quote, and let's get to it.
What Our Customers Say