
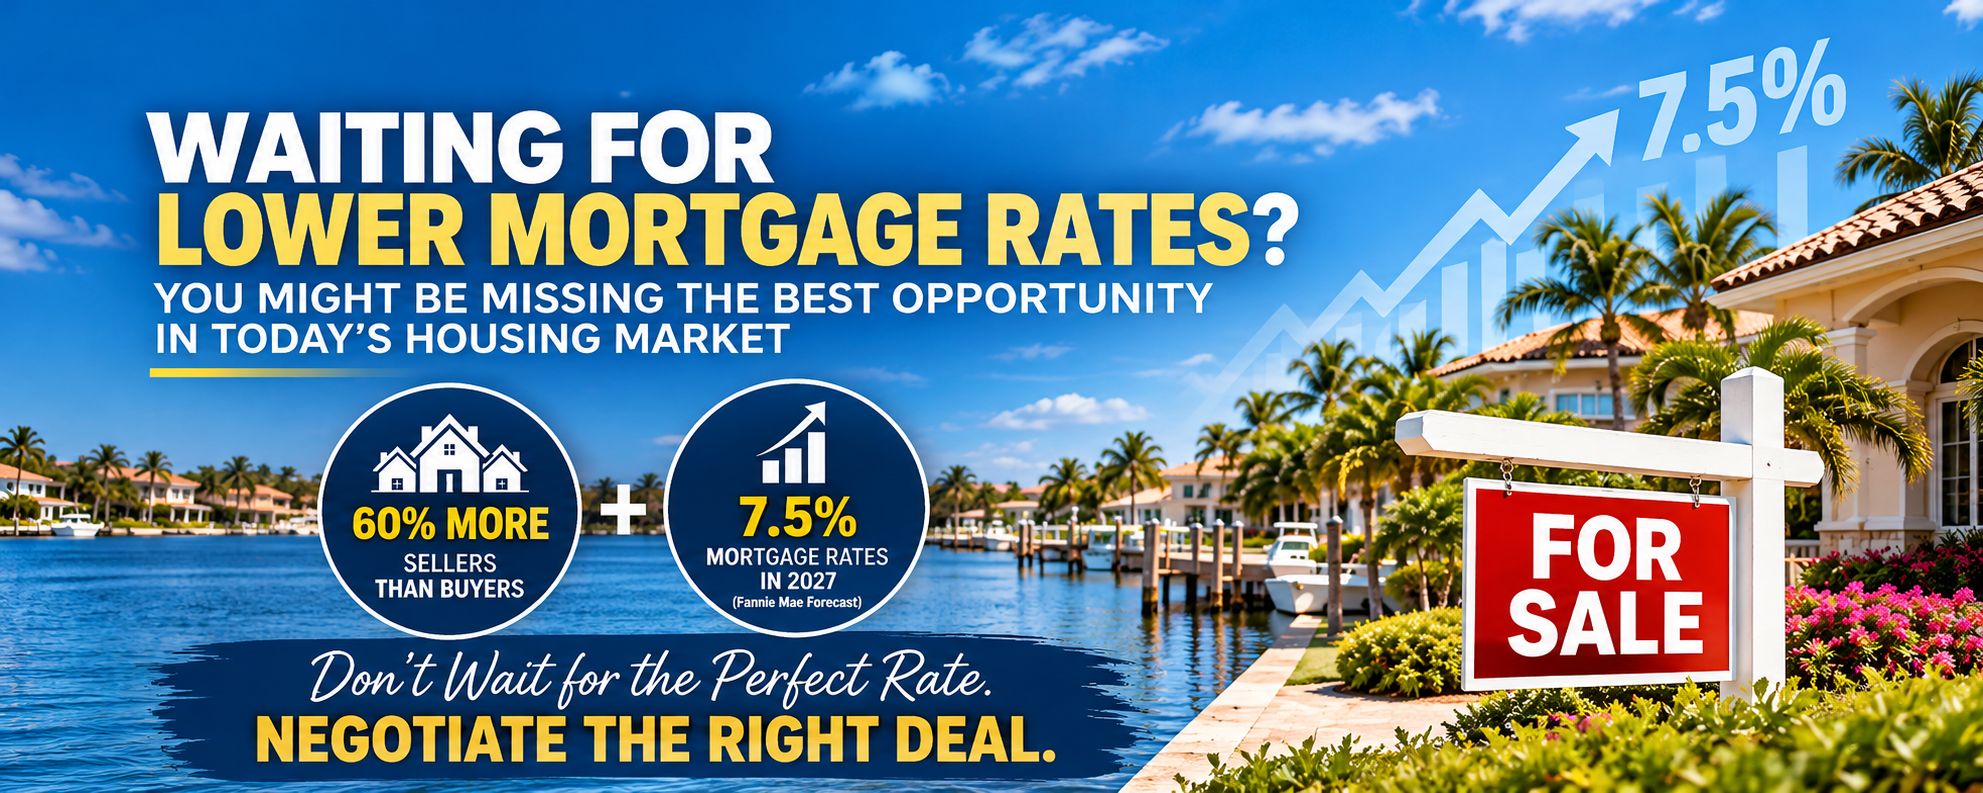
With 60% more sellers than buyers and Fannie Mae forecasting elevated mortgage rates through 2027, today's housing market may offer opportunities worth exploring.
For the past several years, I've had countless conversations with prospective homebuyers who have told me some version of the same thing:
"I'm just going to wait until mortgage rates come down."
And I understand that thinking. When you're making one of the largest financial decisions of your life, you naturally want to get the best possible deal.
But what if waiting for a lower interest rate means missing an opportunity to negotiate a better deal on the home itself?
That's a question worth considering, especially given two significant developments in the housing market.
Last week, we discussed how there are approximately 60% more home sellers than buyers nationwide, according to the market analysis highlighted in our previous article, Fewer Buyers, More Sellers.
Now, Fannie Mae's latest mortgage rate forecast suggests that the lower rates many buyers have been waiting for may not arrive anytime soon.
When you put those two developments together, an interesting opportunity begins to emerge.
Instead of waiting for the mortgage market to improve, perhaps it's time to explore how today's housing market could work in your favor.
Fannie Mae's Latest Forecast: Don't Expect a Return to Low Rates Anytime Soon
According to Fannie Mae's October 2026 Housing Forecast, the agency projects that the average 30-year fixed mortgage rate will reach approximately 7.4% in the fourth quarter of 2026 and remain around 7.5% throughout 2027.
For homebuyers who have been waiting for mortgage rates to return to the 3% or 4% range, that's probably not the news they were hoping to hear.
And while mortgage rate forecasts are never guarantees, they do provide insight into what economists currently expect.
Mortgage rates are influenced by numerous factors, including inflation, Treasury yields, economic growth, and investor expectations.
The reality is that no one can consistently predict exactly when rates will decline or how quickly those changes might occur.
So rather than building your homebuying strategy around something you cannot control, why not focus on the opportunities you can influence?
That's where today's housing market becomes particularly interesting.
Source: Fannie Mae Economic & Strategic Research Forecast, October 2026.
The Housing Market Has Shifted, and Buyers Are Gaining Leverage
Remember what buying a home looked like just a few years ago?
Properties were receiving multiple offers within days, sometimes hours, of hitting the market.
Buyers were offering above asking price, waiving inspection contingencies, and competing against other buyers who were just as desperate to secure a home.
In many cases, sellers were firmly in the driver's seat.
Fast-forward to today, and the dynamics have changed.
As we discussed in last week's blog, there are approximately 60% more sellers than buyers in the national housing market.
That doesn't mean every seller is desperate or that every home is overpriced. Real estate conditions vary considerably by neighborhood, property type, and price range.
But it does mean buyers may have more choices and, in many situations, greater negotiating power.
Think about it from a seller's perspective.
If your home has been listed for 90 days, you've already reduced the price twice, and you're still waiting for a serious offer, how might you respond when a qualified buyer comes along with reasonable terms and a clear path to closing?
You may be much more willing to negotiate than you would have been when there were ten buyers competing for the same property.
And that's where smart homebuyers have an opportunity to create value.
A Great Deal Is About More Than the Purchase Price
When most people think about negotiating a home purchase, they immediately think about asking the seller to lower the price.
And sometimes that's exactly the right strategy.
But a lower purchase price isn't the only way to improve the financial outcome of a real estate transaction.
Depending on the seller's motivation, the property's condition, and the financing program, there may be several ways to structure a more attractive deal.
1. Negotiate Seller-Paid Closing Costs
Closing costs can represent a meaningful expense when purchasing a home.
Rather than paying every eligible closing expense out of pocket, buyers may be able to negotiate a contribution from the seller.
That could allow you to preserve more of your savings for moving expenses, home improvements, or an emergency fund.
2. Explore a Temporary Mortgage Rate Buydown
A temporary mortgage rate buydown can reduce your initial monthly principal and interest payments for a specified period.
For example, a 2-1 buydown generally reduces the effective payment rate by two percentage points during the first year and one percentage point during the second year before returning to the full note rate in year three.
The underlying mortgage interest rate does not change, and borrowers must qualify based on the applicable loan program requirements.
When properly structured, eligible seller concessions may help fund this benefit.
This can provide additional breathing room during the first couple of years of homeownership.
3. Consider a Permanent Rate Buydown
In some situations, negotiating seller concessions to cover discount points may be more beneficial than simply reducing the purchase price.
A permanent rate buydown involves paying an upfront cost to obtain a lower mortgage interest rate.
Whether that makes financial sense depends on the cost, expected time in the home, loan terms, and the potential savings over time.
4. Negotiate Repairs or Property Improvements
Perhaps the home needs a new roof, updated appliances, or other improvements.
Rather than automatically walking away, buyers may be able to negotiate repairs or eligible credits, depending on the property's condition and financing requirements.
The important thing is understanding which negotiating strategy delivers the greatest benefit for your circumstances.
What Could a $10,000 Seller Concession Mean for You?
Let's consider a hypothetical situation.
You've found a home you love, but the seller has had it listed for several months without receiving an acceptable offer.
Instead of requesting a $10,000 reduction in the asking price, you negotiate a $10,000 seller concession toward eligible closing costs or financing expenses.
Depending on your loan program, this could help cover expenses such as loan origination charges, title-related closing costs, prepaid expenses, or discount points.
If you were otherwise planning to pay those expenses out of pocket, that concession could potentially allow you to keep more of your savings available.
Alternatively, using some of the concession toward a permanent mortgage rate buydown could reduce your monthly principal and interest payment over the life of the loan.
Neither option is automatically better than a $10,000 price reduction.
The right answer depends on your down payment, mortgage terms, cash reserves, and how long you expect to keep the loan.
But that's precisely the point.
Today's housing market may give buyers the opportunity to negotiate not just the price of the home, but the financial structure of the purchase itself.
And those opportunities can be extremely valuable.
What Happens When Buyers Return to the Market?
Here's another factor worth considering.
What happens if mortgage rates eventually decline enough to bring a significant number of buyers off the sidelines?
It's reasonable to expect that lower borrowing costs could encourage more prospective buyers to begin shopping.
And when more buyers compete for available homes, sellers may have less incentive to negotiate.
We could see shorter marketing times, fewer seller concessions, and increased competition in certain neighborhoods and price ranges.
Of course, that outcome isn't guaranteed. Inventory levels, economic conditions, employment, and local market dynamics will all play a role.
But the possibility raises an important question:
Would you rather compete with fewer buyers while negotiating more favorable terms, or wait for a potentially lower mortgage rate in a more competitive market?
There isn't one correct answer for everyone.
However, I believe too many prospective buyers are focusing entirely on the possibility of lower mortgage rates without considering what they may be giving up in negotiating power.
Southwest Florida Buyers Have an Opportunity Worth Exploring
Here in Southwest Florida, buyers have been navigating a changing real estate market.
From Venice and North Port to Englewood, Sarasota, and Punta Gorda, properties vary widely in price, condition, location, and how long they've been listed for sale.
Some homes are priced appropriately and sell quickly.
Others remain on the market longer, creating potential opportunities for buyers willing to explore their options.
This is where having the right team becomes especially valuable.
An experienced Realtor can help identify properties where sellers may be more motivated to negotiate.
And an experienced mortgage advisor can help evaluate different financing structures to determine which options may provide the greatest benefit.
For example, would you be better served by negotiating a lower purchase price, asking the seller to contribute toward closing costs, or exploring a mortgage rate buydown?
The answer isn't always obvious.
But with the right information, you can make a decision based on your financial goals rather than simply hoping mortgage rates will improve.
Don't Wait for the Perfect Interest Rate. Negotiate the Right Deal.
I want to be clear about something.
I'm not suggesting that everyone should rush out and purchase a home tomorrow.
Buying a home is a significant financial commitment, and the timing needs to make sense for your personal circumstances.
You should have confidence in your income, understand your monthly housing expenses, and maintain an appropriate financial cushion.
And you should never purchase a home based on the assumption that you'll be able to refinance into a lower interest rate later.
But if you're financially prepared, have stable income, and are planning to purchase a home in the foreseeable future, I would encourage you to take another look at today's market.
Because while everyone else is waiting for interest rates to improve, you may have an opportunity to negotiate terms that weren't available just a few years ago.
The perfect interest rate may never arrive.
The perfect housing market certainly doesn't exist.
But the right opportunity, combined with thoughtful negotiation and a sound financing strategy, could make homeownership a reality sooner than you expected.
You can't control where mortgage rates go next year. But you can take advantage of the opportunities available in today's market.
Let's See What We Can Negotiate
If you've been sitting on the sidelines waiting for mortgage rates to fall, perhaps it's time for a fresh conversation.
At Gulfside Mortgage Services, we believe that home financing should be about more than simply securing a loan.
It's about helping you understand your options, evaluate opportunities, and make confident decisions that support your long-term financial goals.
Whether you're purchasing your first home, relocating to Southwest Florida, or considering your next real estate investment, I'd welcome the opportunity to help you explore your financing options.
Let's look at the numbers, evaluate your options, and see if we can structure a deal that works in your favor.
Kevin Corbett
Veteran Mortgage Advisor
Gulfside Mortgage Services
Powered by The Mortgage Firm
Schedule a Mortgage Consultation
Sources
- Fannie Mae, October 2026 Economic & Housing Forecast
- CNBC, October 14, 2026: Fannie Mae Sharply Raises Mortgage Rate Forecast for 2027
- Fewer Buyers, More Sellers, Gulfside Mortgage Services
Disclaimer: Mortgage rate forecasts are estimates and subject to change. Seller concessions, temporary buydowns, permanent buydowns, and closing-cost credits are subject to loan program guidelines, eligibility requirements, and applicable limits. This article is for educational purposes and does not constitute a commitment to lend or an offer of specific financing terms.
Share


RECENT ARTICLES
Free Guides & Resources
Our favorite kind of buyer? A confident one. Brush up on your loan knowledge, get an accurate quote, and let's get to it.
What Our Customers Say